
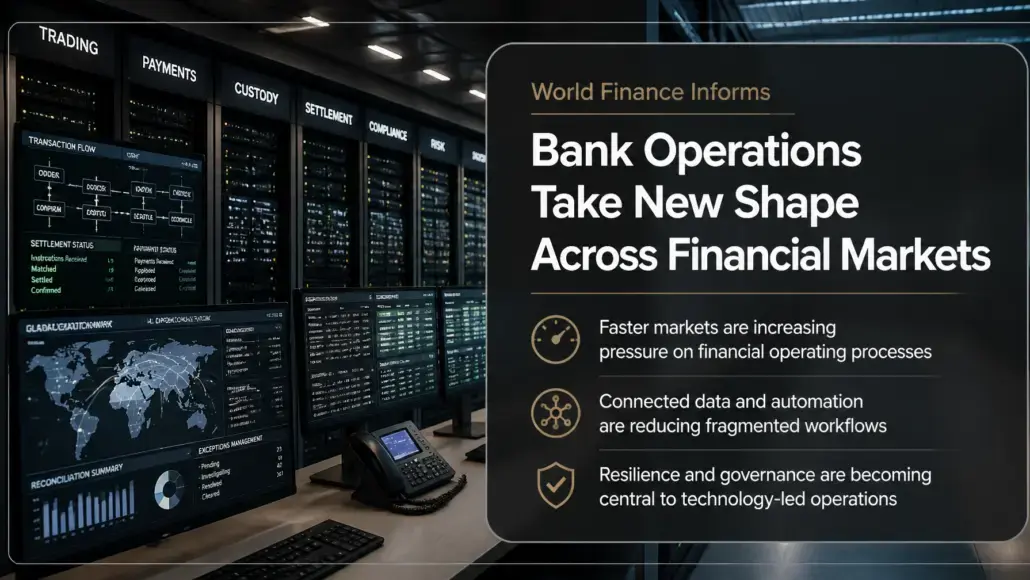

Financial markets are becoming faster, more data-intensive and more interconnected, putting pressure on the processes banks use to execute, reconcile and control transactions. Faster settlement cycles, structured financial data, digital infrastructure and expanding automation are changing how work moves between trading, payments, custody, settlement, compliance and risk functions. Bank operations are consequently becoming less focused on individual processing tasks and more dependent on connected workflows that can handle activity with greater speed and consistency.
Faster Markets Reshaping the Operating Model
The shift is particularly visible in post-trade and transaction processing. As settlement timelines become shorter, institutions have less time to identify exceptions, validate instructions and resolve discrepancies before transactions need to complete. Processes that previously relied on spreadsheets, email exchanges or manual intervention can therefore create greater operational pressure. The move toward richer structured data is also changing the information available to institutions, supporting greater automation and reducing the need for repeated manual interpretation. Several areas are becoming particularly important:
- Settlement – Shorter processing windows are increasing the need for timely, accurate instructions and faster exception resolution.
- Data – More structured and granular financial information can support automation, analytics and improved transaction visibility.
- Reconciliation – Growing transaction volumes make automated matching and exception management increasingly important for reducing operational friction.
- Straight-through processing – Greater automation can allow transactions to move through multiple stages with less manual intervention.
The broader change is not simply about making individual processes faster. It is about redesigning how financial-market activities connect across an institution. Payments, securities processing, collateral, reconciliation, reporting and control functions increasingly depend on common data and coordinated workflows. ISO 20022, for example, is designed to provide richer structured data and support end-to-end automation across financial messaging, while the transition toward faster settlement is exposing weaknesses in fragmented operational processes. For banks, this means bank operations are increasingly becoming an infrastructure question as much as a staffing or process question. The quality of the underlying systems, data and connections can determine how effectively an institution responds when transaction volumes rise, settlement windows contract or market conditions change.
Connected Infrastructure Replacing Fragmented Processes
The next stage of operational change is increasingly centred on how different systems and functions work together. A bank may already have automated individual processes, but fragmented platforms, inconsistent data and disconnected workflows can prevent those improvements from producing an integrated operating model. Bank operations therefore depend increasingly on the ability to connect processes across the transaction lifecycle. Several capabilities are becoming central:
- Automation – Repetitive validation, matching, reporting and processing tasks can increasingly be handled through automated workflows.
- Data quality – Structured, consistent data reduces ambiguity and supports more reliable processing across connected systems.
- Workflow integration – Linking front-, middle- and back-office processes can reduce hand-offs and duplicated work.
- Exception management – As routine processing becomes more automated, operational teams can focus more heavily on transactions and events requiring judgement.
The importance of connected infrastructure is also reflected in the Basel Committee’s operational-resilience framework, which treats critical-operation interdependencies, third-party dependencies, business continuity and resilient ICT as interconnected elements of a bank’s ability to continue operating through disruption. 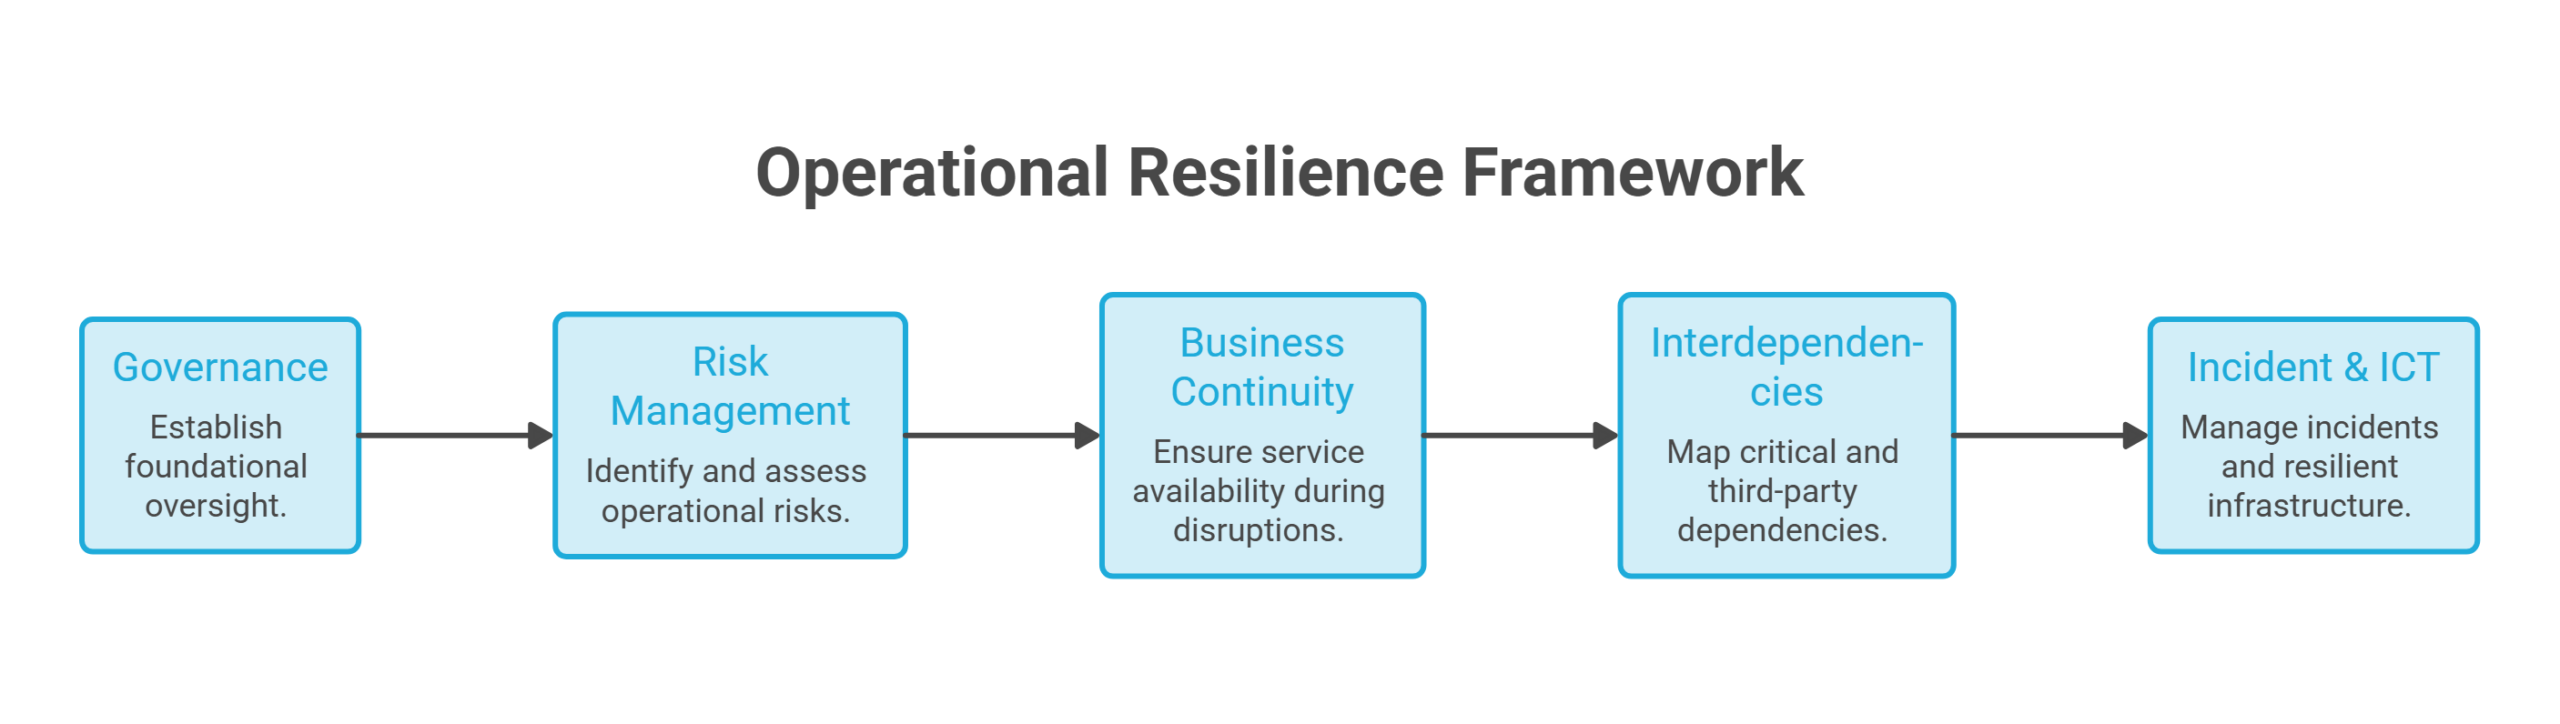 The framework shows why operational transformation cannot be separated from the infrastructure and resilience supporting critical financial services.
AI Adds Speed but also New Operational Dependencies
AI is adding another layer to this transformation. Financial institutions are using AI across operational and service processes, while banks and market firms are also exploring applications in analytics, surveillance, coding, data processing and other functions. The potential benefit is greater speed and capacity, but the technology introduces new dependencies that must be incorporated into operating models. These considerations include:
- AI governance – Institutions need clear accountability for how AI systems are selected, deployed and monitored.
- Third-party risk – Dependence on external cloud, model and technology providers can create concentration and continuity risks.
- Cyber resilience – More connected systems can create additional attack surfaces and increase the importance of response and recovery capabilities.
- Model oversight – AI-generated outputs require appropriate controls, validation and human judgement where the consequences of error are material.
The FSB has identified third-party dependencies, cyber risks, model risk, data quality and governance as important considerations as financial institutions expand AI adoption. As a result, bank operations are not simply becoming more automated. They are becoming more dependent on the quality of the technology ecosystem surrounding them. That makes operational resilience increasingly connected to how institutions manage technology, infrastructure and critical financial-market services.
Operational Resilience Becoming Core Banking Capability
The transformation of financial-market processes is ultimately changing what banks need from their operating models. Speed and automation can improve efficiency, but they also increase the importance of resilient infrastructure, reliable data, strong controls and clear recovery mechanisms. A technology failure, cyber incident or disruption at a critical third-party provider can affect a bank’s ability to deliver essential services even when its capital and liquidity positions remain strong. The strategic direction is therefore toward operating models that combine bank operations efficiency with resilience. Institutions that can connect processes, standardise data, automate routine activity and maintain effective oversight will be better positioned to handle increasingly demanding financial-market environments.
References
- Bank for International Settlements – Basel Consolidated Guidelines: Operational Resilience – 2026
- Bank for International Settlements – Project FuSSE: Exploring Flexible, Scalable and Secure Settlement Engines – 2026
- Financial Stability Board – Sound Practices for Responsible Adoption of Artificial Intelligence (AI): Consultation Report – 2026
- Financial Stability Board – Monitoring Adoption of Artificial Intelligence and Related Vulnerabilities in the Financial Sector – 2025
- Swift – ISO 20022 for Financial Institutions – 2026
- S&P Global – From Manual SSIs to T+1: Why Data, Automation, and AI Are Redefining Settlement – 2026