

Wealth management firms are expanding access to private equity, private credit, infrastructure and real estate investments through new fund structures and digital distribution channels. Historically, many of these investments were concentrated among institutional investors and eligible high net worth clients because of higher entry requirements, complex documentation and limited liquidity.
Digital wealth platforms are increasingly reaching wealth management channels through professionally managed funds, digital subscription processes and investment platforms that simplify administration and reporting. The CFA Institute’s July 2026 research describes private credit as a US$2.6 trillion global market and examines its growing distribution through semi liquid funds, interval funds, non traded business development companies and digital platforms. However, easier access does not remove the underlying investment risks or make every product suitable for every investor.
Digital Distribution is Changing Access to Private Investments
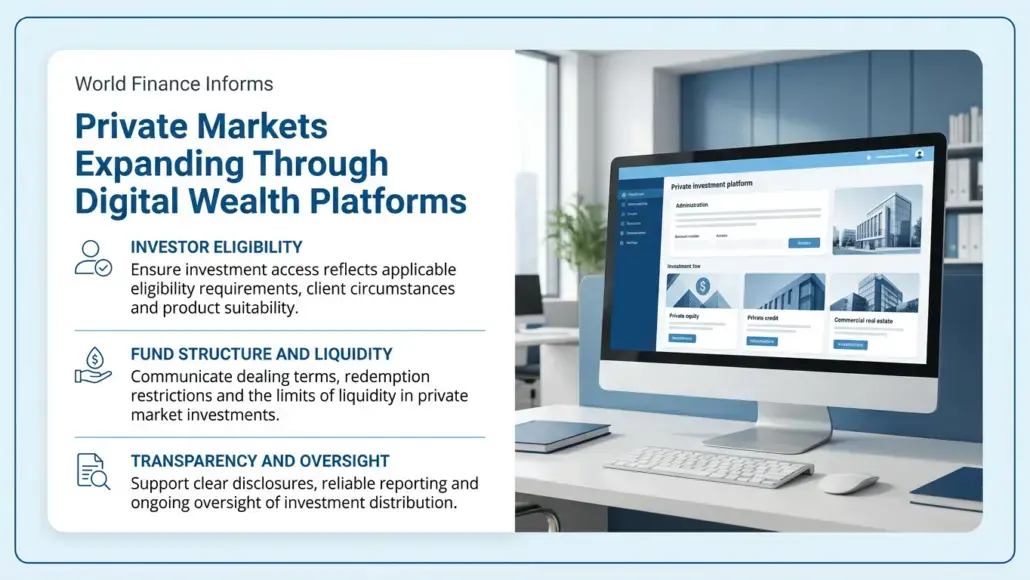
Digital platforms can simplify investor eligibility checks, subscriptions, documentation, portfolio reporting and ongoing servicing. They also allow wealth managers to incorporate private market products into broader investment offerings, subject to applicable requirements and product restrictions. Digital wealth platforms nevertheless differ from publicly traded investments in important respects. Valuations may rely on periodic assessments, underlying assets can be difficult to sell quickly, and withdrawal opportunities depend on the structure and terms of the investment vehicle. Wealth managers must therefore evaluate not only whether a product can be offered digitally, but also whether their systems can support its administration, reporting and liquidity requirements throughout the investment lifecycle.
Key distribution considerations include:
- Investor eligibility: Confirm that clients meet the applicable legal, financial and product specific requirements.
- Product administration: Coordinate subscriptions, documentation, valuations and ongoing portfolio reporting.
- Investment transparency: Explain fees, underlying exposures, valuation methods and withdrawal conditions.
- Operational readiness: Ensure platform processes can support the product beyond the initial investment transaction.
Platform distribution can broaden access, but digital wealth platforms require product specific controls and clear communication about the difference between convenient digital transactions and the ability to realise an investment.
New Fund Structures are Broadening Wealth Distribution
Evergreen funds and other semi liquid investment vehicles are becoming more prominent in the distribution of private assets. MSCI’s March 2026 research reported that evergreen private market funds were approaching US$500 billion in assets, with wealth investors representing around one fifth of assets under management in these structures. Such funds may permit ongoing subscriptions and periodic redemption opportunities, subject to their terms.
This differs from traditional closed end funds, which typically operate over a defined investment period. Digital wealth platforms are therefore becoming accessible through a wider range of structures, but these arrangements do not eliminate the difficulty of selling underlying assets when investors request withdrawals.
- Fund structure: Understand whether the vehicle is closed end, evergreen, interval based or subject to other redemption arrangements.
- Liquidity management: Examine notice periods, withdrawal limits and the potential for redemption restrictions.
- Valuation practices: Explain how often holdings are valued and how estimates differ from observable market prices.
Investor Protection Must Keep Pace with Distribution
Recent regulatory developments show why access, liquidity and suitability must be considered together. In September 2026, the US Securities and Exchange Commission proposed amendments intended to expand access to private investments through regulated fund structures, including changes to interval fund arrangements. In October, the UK Financial Conduct Authority consulted on proposed redemption terms for authorised funds investing in illiquid assets.
Australia’s securities regulator also issued an interim stop order concerning distribution of the Ares Global Credit Income Fund, citing concerns about whether its target market determination matched the needs and risk capacity of intended retail investors. These are jurisdiction specific developments, and some measures remain proposals rather than final rules.
For private markets, wealth managers and platform providers should prioritise:
- Suitability: Match product risks, liquidity and investment horizons to client circumstances.
- Clear disclosures: Explain fees, valuation practices, withdrawal restrictions and potential losses.
- Distribution oversight: Ensure product descriptions and target market assessments accurately reflect the investment.
Digital distribution makes administration easier, but it cannot replace due diligence, appropriate product selection or ongoing oversight.
Building Responsible Access to Private Investments
The expansion of digital distribution creates opportunities for wealth managers to offer a broader range of investments, but the quality of the service depends on how well firms manage access, administration and investor protection. Product structures, valuation practices and liquidity terms must remain understandable throughout the client relationship. As technology becomes more involved in product discovery, client matching and investment servicing, firms must also address AI governance.
Key priorities include:
- Explain product structures and liquidity restrictions before investment.
- Maintain reliable reporting, suitability checks and distribution oversight.
- Align platform capabilities with the operational demands of each investment vehicle.
Ultimately, wider access will be sustainable only when digital convenience is supported by transparent terms, appropriate client selection and disciplined investment oversight.
References
- CFA Institute. Private Credit: Market Structure, Fund Design, and Retail Access. July 2026.
- MSCI. The Ascendance and Implications of Evergreen Funds in Private Markets. March 2026.
- US Securities and Exchange Commission. SEC Proposes Amendments to Expand Responsible Retailization of Private Markets. September 2026.
- UK Financial Conduct Authority. Fair Redemption Terms for Authorised Funds Investing in Illiquid Assets. October 2026.
- Australian Securities and Investments Commission. ASIC Issues DDO Stop Order Against Fidante Partners Limited for TMD Deficiencies. October 2026.