

Britain’s largest banks have completed live interbank transactions using tokenised deposits, marking the first time commercial-bank money has moved between separate financial institutions through shared blockchain-based infrastructure. The milestone emerged from the Great British Tokenised Deposit project, a collaborative initiative involving seven of the country’s most prominent banking groups: Barclays, HSBC UK, Lloyds Banking Group, Monzo, Nationwide, NatWest and Santander.
Tokenised deposits are ordinary bank deposits represented on blockchain infrastructure. Unlike privately issued stablecoins, they retain their full legal status as commercial-bank money, meaning funds remain within the regulated banking system. The critical advance demonstrated by this project is interoperability. Rather than each bank developing an isolated blockchain system, a limitation that had stalled interbank digital-money transfers for years, the participating institutions operated through a shared platform that allowed tokenised deposits to flow seamlessly between them.
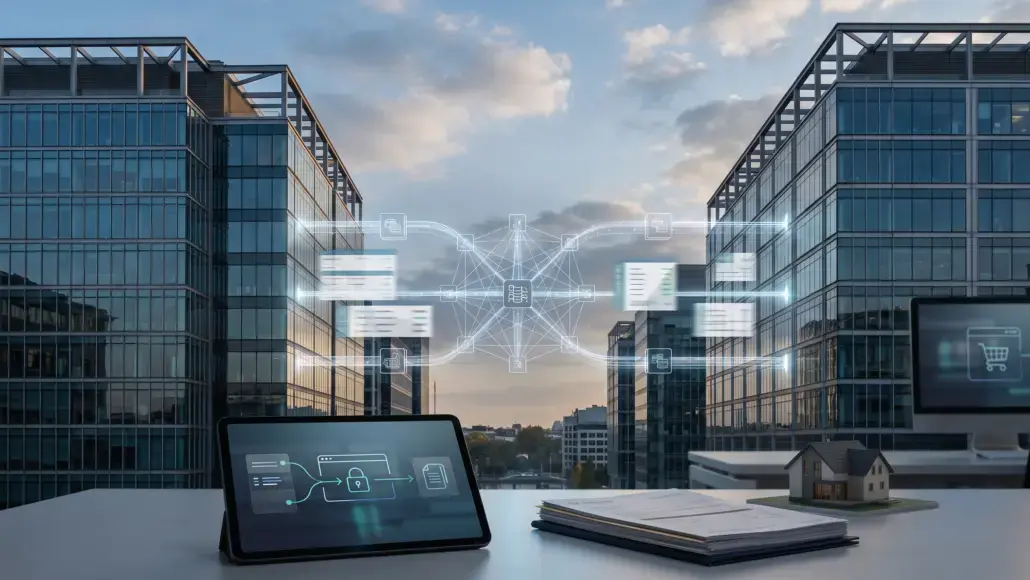
The completed transactions included two remortgage completions and one simulated consumer marketplace purchase. In the remortgage transactions, Lloyds, NatWest and Barclays used tokenised deposits to automate fund releases. Once each property transaction reached completion, locked funds were released automatically without manual intervention, demonstrating the potential of programmable money to streamline settlement in complex financial processes.
Live Transactions Demonstrate Programmable Payments Across Banks
The consumer marketplace transaction involved a group of banks including HSBC and tested a scenario modelled on an online purchase. Programmable deposits allowed funds to be held securely in the buyer’s account and released to the seller only after delivery was verified. It is important to note that no actual goods changed hands during this test, the transaction was a simulation designed to validate the infrastructure and the programmability features underpinning tokenised deposits.
These interbank payments represent a significant operational proof point. The ability to programme conditions into tokenised deposits, releasing funds only when predefined criteria are met, has direct implications for fraud reduction, settlement efficiency and the broader architecture of digital finance. For payments professionals and financial-infrastructure executives, the project demonstrates that blockchain banking can operate across institutional boundaries in a live environment, not merely within a single bank’s internal systems.
Next Steps Toward Production and Digital Bond Issuance
With live transactions now completed, the participating banks are moving toward the next phase of development. The project plans to establish a dedicated company and develop a formal rulebook and governance framework to support the transition from pilot stage into full production. These steps are designed to provide the regulatory clarity and operational standards required for broader adoption of tokenised deposits across the banking sector.
Looking further ahead, the consortium of banks intends to issue three digital bonds in the first quarter of 2027. These bonds would be tradeable and settlable using tokenised deposits, extending the infrastructure’s utility from interbank payments into capital markets. That phase of work remains in the planning stage and has not yet been executed, but it signals the direction in which participating institutions aim to take this shared digital finance platform.